In my opinion, soybeans will generate some positive profit for farmers and become a kind of lifeline, allowing them to receive funds in the first months after harvest. Roughly speaking, to receive the same amount of money, a farmer would need to sell 1 tonne of soybeans or 3 tonnes of wheat. Therefore, soybeans will compete for their place in the logistics chain with wheat and corn. And I believe soybeans will find their market, especially considering that two major soybean buyers are located close to Ukraine’s borders: the EU and Türkiye. Ukrainian exporters will find a way to supply their customers with both genetically modified and non-GM soybeans.
The Soybean Equation: Can the Crop Offset Ukrainian Farmers’ Losses?
20 October 2026, 06:19 1915
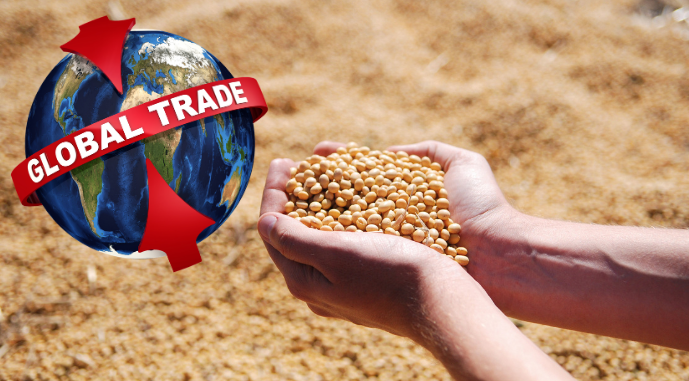
Soybeans could become one of the crops delivering positive margins for Ukrainian farmers this season. They offer higher profitability and greater export attractiveness compared with grain crops: to generate comparable revenue, a farmer needs to sell approximately 1 tonne of soybeans versus 3 tonnes of wheat.
These estimates were presented by Ukrainian agricultural market participants during AgroFoodSummit in Mersin, Türkiye.
According to Andrii But, Head of Foreign Trade at AGROTRADE Group, under the current circumstances, given rising logistics costs and low grain prices, wheat and corn may generate negative margins for farmers.
Andrii But, Head of Foreign Trade at AGROTRADE Group
Anton Zhemerdieiev, Commercial Director at TAS Agro, confirms that the EU remains one of the most promising destinations for Ukrainian soybeans, particularly non-GM products, which can be sold at a premium.
According to him, the main problem at present is logistics. Black Sea ports are closed, which has led to a sharp increase in freight rates on the main maritime markets.
Due to logistics problems, Ukraine has lost access to certain markets and, for example, cannot supply soybeans to Pakistan. Egypt has also significantly reduced its purchases of Ukrainian soybeans. In 2025, around 5 million tonnes of soybeans arrived at Egyptian ports, most of them from the United States. Egypt became the second-largest consumer of US soybeans after China. Egyptian traders note that soybean purchases are not only about price, but also about reliability of supply, consistent quality and uninterrupted transportation.
The situation with blocked ports effectively narrows the opportunities for Ukrainian soybeans to a single market — the EU. Given this, experts do not expect particularly high premiums for non-GM soybeans. Traders forecast that suppliers have a realistic chance of securing a premium for non-GM soybeans until 30 December, when buyers will seek to purchase consignments before that date.
Therefore, finding markets that offer higher added value remains important for Ukrainian soybean producers, although export opportunities depend to a large extent on logistics and delivery costs.
Small farmers who cannot independently organise logistics to access foreign markets will most likely sell their products to processors. According to experts, soybean processing in Ukraine offers a margin, but today this business is accompanied by significant war-related risks, while the issue of ensuring efficient sales of soybean meal also remains.
Analysing the global soybean market, Atria Brokers co-founder Jan Kozyrytskyi noted that production currently exceeds 442 million tonnes. The global soybean market now depends on the situation in Brazil and on decisions by China, which remains the key buyer. The pace of purchases and the choice between Brazilian and US soybeans will influence global prices. The analyst describes China as a «black box», as there is no clear understanding of its plans: purchase volumes, existing soybean stocks or processing volumes.
Jan Kozyrytskyi, co-founder of Atria Brokers
Brazil is the world’s main and largest soybean producer, but practically the entire soybean crop grown in the country goes to China. Brazil accounts for around 62% of global production, while China accounts for approximately 60% of global consumption. Therefore, if China refuses to make purchases or postpones them, this means that the entire market will depend on its decisions.
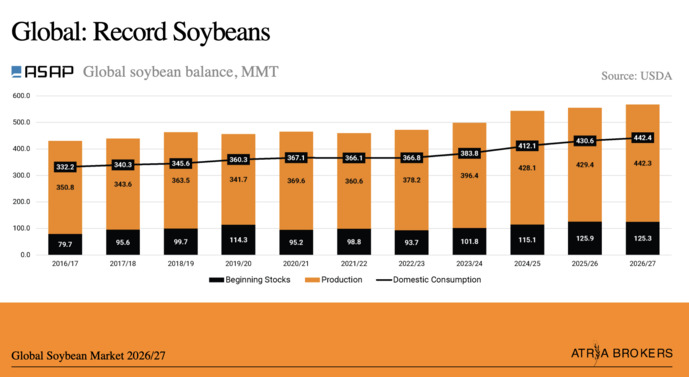
As for Ukraine, Jan Kozyrytskyi notes that Ukrainian soybeans could become a good alternative for Mediterranean countries, including Türkiye, when global exporters are unable to ensure supplies at the required time. Such a situation is entirely possible due to weather risks, particularly in Brazil, as well as logistics problems or changes in trade flows between Brazil, the United States and China.
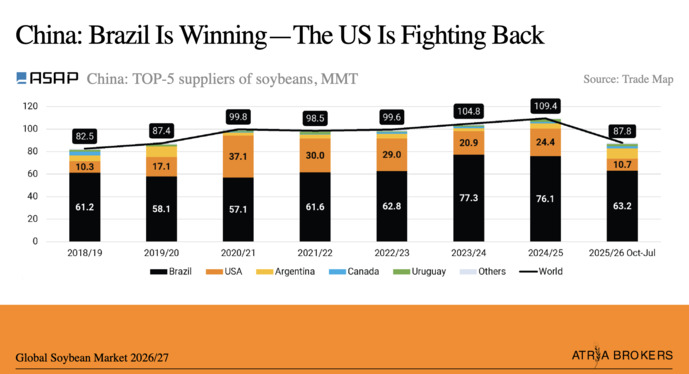
Such signals are already emerging in the market: according to a forecast by Brazil’s National Supply Company (Conab), the world’s largest soybean producer and exporter may record the slowest pace of expansion in soybean planting area in the past 20 years in the 2026/27 marketing year. Soybean area is forecast to increase by only 1.4% to 49.3 million hectares. This would be the weakest growth since the 2006/2007 season. The main reasons for the slowdown in planting expansion are declining production profitability and rising costs. Additional uncertainty is being created by weather risks associated with a possible strengthening of El Niño.
Jason John, Regional Head of Market Intelligence for the Middle East, North Africa and South Asia (MENASA) at the US Soybean Export Council (USSEC), points out that the latest USDA October report on soybean crop volumes contains some interesting data: Brazil’s soybean crop for the 2026/2027 season is forecast at 186 million tonnes. At the same time, Brazil’s domestic agency Conab provides a somewhat more conservative estimate of 181.6 million tonnes, while private market participants put the figure at 183 million tonnes.
Jason John, Regional Head of Market Intelligence for MENASA at the US Soybean Export Council
There is a discrepancy of 6.2–6.5 units between USDA data and the figures provided by private market participants. The question is how this will affect prices. Of course, it must be taken into account that additional pressure on the market is coming from geopolitics and trade policy, as well as climate change and changes in the global supply chain.
Analysts emphasise that even a small decline in production in Brazil could remove millions of tonnes of soybeans from the global market and increase demand for alternative suppliers. At the same time, major soybean buyers are already prepared for the possibility that, if supplies are disrupted due to weather or logistics problems, their next soybean shipment will not come from Brazil.
Liudmyla Lebid, AgroPortal.ua

 14 October 2026, 07:201228
Chickpea and Lentil Paste: How One of the World's Largest Legume Processing Plants Operates
 02 October 2026, 07:201482
Shifting Trade Flows: What Opportunities Are Available to Ukrainian Producers?
 18 September 2026, 07:201691
CraftUP Ukraine: Finalists Presented Their Business Projects and Received Grants
- 20 October 2026, 08:00 297
 Free Trade with Türkiye: What Advantages Ukrainian Agricultural Exporters Gain
The Free Trade Agreement between Ukraine and the Republic of Türkiye, which entered into force on 1 October this year, opens up new opportunities for Ukrainian agricultural producers and processors by creating more favourable conditions for access to one of the region’s key markets.
- 14 October 2026, 07:20 1228Chickpea and Lentil Paste: How One of the World's Largest Legume Processing Plants Operates
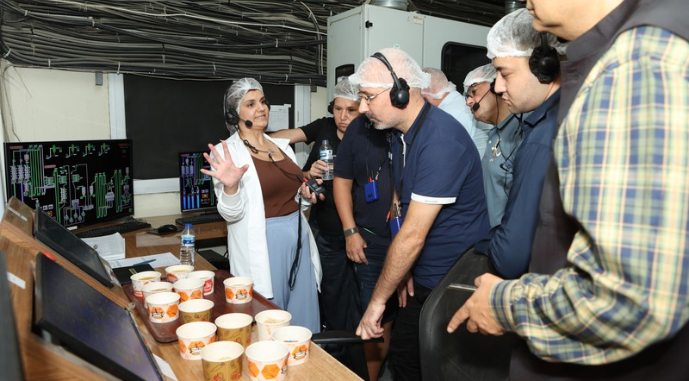
Participants of AgroFoodSummit, which took place in Mersin, Türkiye, at the end of September and was organised by the Ukrainian Pulses and Soybean Association, visited Arbel, one of the largest exporters and processors of pulses. Visitors saw how products are made — from raw materials through processing and preparation for shipment to international markets.
- 18 July 2026, 08:00 4283
 Attacks on the Ports of Greater Odesa: Rising Logistics Costs Remain the Most Sensitive Challenge
After more than four years of full-scale war, Ukraine’s agricultural sector has learned to operate under constant logistics risks. As a result, scenarios involving partial disruptions to port operations have long been incorporated into the day-to-day operations of TAS Agro.